New Book Launch · Coming Soon
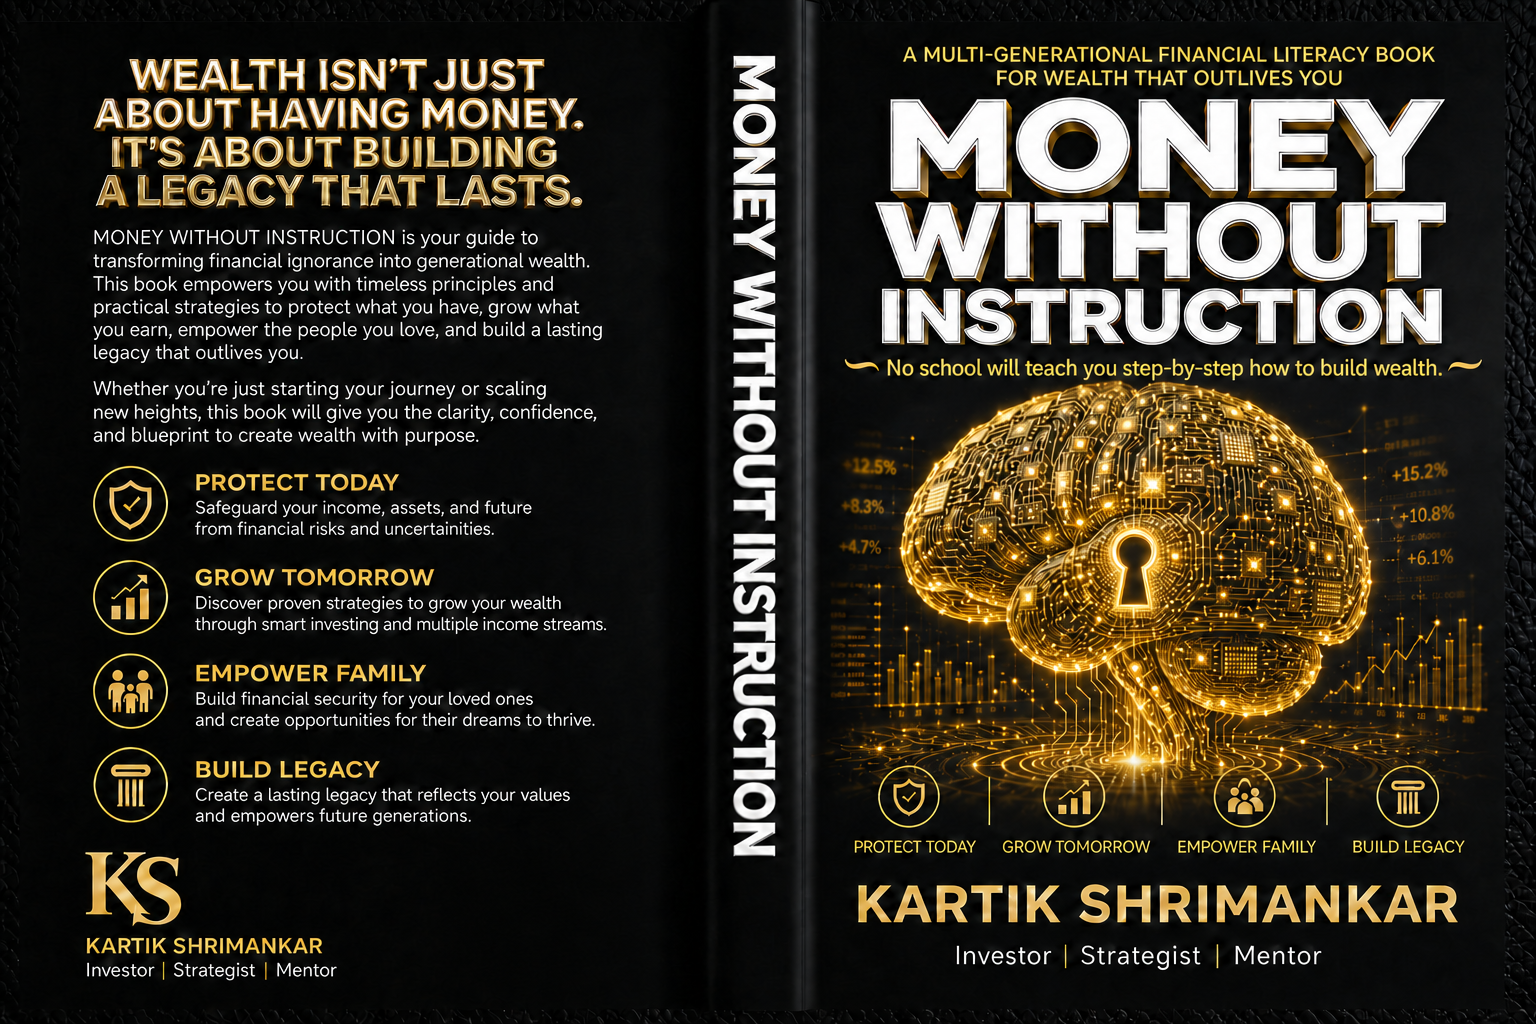
Money Without
Instruction
Everyone Has Money.
Almost No One Knows How to Use It.
Scroll Down
Everyone Has Money.
Almost No One Knows How to Use It.
You earn 50k, 100k, even 150k — and somehow, it still feels like you're falling behind.
That's not a coincidence. Schools teach you how to earn money. Almost no one teaches you what to do with it once you have it. The result? Hard-working families stay trapped in a cycle of financial stress — not because they don't earn enough, but because they were never given the instructions.
MONEY WITHOUT INSTRUCTION is the manual that was missing.
A complete blueprint to protect, grow, empower, and build a legacy that outlives you.
Safeguard your income, assets, and future from financial risks and uncertainties.
Discover proven strategies to grow your wealth through smart investing and multiple income streams.
Build financial security for your loved ones and create opportunities for their dreams to thrive.
Create a lasting legacy that reflects your values and empowers future generations.
No matter where you are in life, there's a blueprint waiting for you.
Ages 10 – 14
Plant the seeds of financial literacy before bad habits take root. This section teaches kids how money works in the real world — saving, spending with purpose, and thinking long-term. By the time they reach high school, they'll already be ahead of most adults.
Ages 15 – 22
Enter adulthood with a financial head start. Learn how to avoid the debt traps that swallow most young adults, start investing early with whatever you have, and build income streams while you're still in school or starting your first job.
Ages 23 – 40
This is your wealth-building window. Turn your income into assets, create multiple revenue streams, protect what you're building, and lay the groundwork for generational wealth. The decisions you make in this decade define the next fifty years.
Ages 40 – 60+
It's never too late to course-correct. Whether you're catching up or scaling up, this section shows you how to accelerate wealth, protect your family's future, and build a legacy plan that ensures everything you've worked for outlives you.
Early in my career, as my income began to climb, I caught myself falling into a subtle trap. I thought that earning more money meant it was time to "look" like I was earning more money. I started spending on things I didn't actually need — brand-name clothes, designer shoes, expensive dinners out, and upgrade after upgrade. My paycheck was bigger, yet at the end of every month, my savings account looked almost identical to when I was making half as much.
It took years — and a closet full of expensive items that I eventually ended up donating or selling for pennies on the dollar — to realize the truth: I was paying a heavy invisible tax just to project an image.
We live in a world designed to make you feel financially inadequate. Every advertisement, corporate environment, and social media feed is engineered to convince you that your current life isn't enough. If you don't actively build a psychological defense system against social comparison, your income will never be large enough to build real wealth.
It is natural to look around at colleagues, neighbors, or friends and evaluate where you stand. But in modern finance, comparison is the quickest way to ruin a household budget.
When you look at someone driving a luxury $70,000 car or wearing high-end designer gear, your brain automatically translates that vision into "wealth." What you are actually seeing is spending.
You have no idea how much debt is sitting behind that steering wheel. During my years working in banking, I saw this contrast constantly. People who looked exceptionally wealthy on the outside were often one missed paycheck away from complete insolvency, trapped under massive car loans and credit card balances. Meanwhile, the real millionaires often walked in wearing plain clothes and driving ten-year-old sedans.
I learned to reframe how I view comparison. When I see peers driving high-end vehicles, I don't feel the need to keep up anymore. I remind myself that my paid-off, practical vehicle isn't a sign of lack — it's a conscious choice to keep capital in my family's balance sheet where it can compound quietly.
Every dollar you spend to project "visible wealth" is a dollar stolen from your actual net worth. When your income increases, the single most dangerous temptation is lifestyle creep — the quiet tendency to expand your standard of living to match your new earnings.
When my pay went up, I fell right into this trap. Instead of directing that extra cash flow into investments or savings, I funneled it into non-essential upgrades. It produced short-term dopamine, followed by long-term regret. Looking back, those thousands of dollars could have bought real security, paid down debt faster, or funded future goals for my children.
To overcome the visible wealth tax, you have to redefine success. Real wealth is invisible. Wealth is the money you haven't spent. It is the peace of mind that comes from zero bad debt, a solid emergency fund, and freedom from financial anxiety.
If you think social pressure used to be tough, today's digital environment has amplified it a thousand times over. Social media algorithms are explicitly designed to show you short, polished clips of people living like there is no tomorrow. You see lavish vacations, luxury unboxings, and high-end lifestyle reels. It triggers a sudden, powerful itch to spend — a feeling that you are missing out on the good life.
The dangerous lie of social media reels is that they show the consumption, but hide the bill.
People live online as if tomorrow will never come. But tomorrow does come. And when it arrives, the fleeting excitement of that impulse purchase vanishes, leaving behind credit card statements and financial stress. Comparing your real daily life to someone else's edited highlight reel is a guaranteed way to make terrible financial decisions.
To protect my family from impulse spending and digital traps, we use a simple, repeatable framework anchored by two core questions: Needs vs. Wants and Borrow/Used vs. New.
Whether I am evaluating a purchase for myself or having a daily conversation with my daughter as she prepares for college, this is the exact logic we apply:
By applying this buffer, you instantly eliminate 80% of wasteful spending while still getting what you actually need.
As parents, one of our primary jobs is to help our children navigate peer pressure before they step out into the real world. I make it a point to talk with my daughter regularly about these exact principles. When she brings up a new item or trend, we don't start with a harsh "No." We open a dialogue around self-worth and purpose.
I tell her: Never compare your life, your goals, your money, or your journey with anyone else.
When young adults rely on brand-name clothing, expensive tech, or social media flexes to feel valuable, they are building their self-esteem on shaky ground. True self-confidence doesn't come from what you wear or drive; it comes from knowing who you are, understanding your goals, and having the internal discipline to achieve whatever you set your mind to.
When you stop caring about proving yourself to strangers, you unlock the ultimate financial cheat code: You get to keep your money.
1. Identify One "Visible Wealth" Leak: Look back over your bank statements from the last month. Find one category where you've been spending money primarily out of habit, convenience, or image. Calculate how much that leak costs you annually.
2. Implement the 48-Hour Rule: Pick an item currently sitting in an online shopping cart or on your wish list. Apply the 48-hour buffer. Wait two days, ask if it's a true need, and check if it can be borrowed or bought used before spending a single dollar.
Everything you need to know before the book launches.
Absolutely. Whether you've never invested a dollar or you're already managing a portfolio, the book starts with fundamentals and builds step by step. No finance background needed — just a willingness to learn.
Not at all. The book is written in plain language with real-world examples from the author's banking and corporate career. Every concept is explained clearly, with practical frameworks you can apply immediately.
Yes. The book is specifically designed for four age brackets, starting at ages 10–14. Each section is tailored to the reader's life stage, so you can read it yourself and share the relevant chapters with your kids.
The book will be available in paperback and digital (ePub & PDF) formats. Kickstarter backers will have access to exclusive tiers and rewards once the campaign goes live.
The Kickstarter campaign is coming soon. Subscribe to our newsletter above to be the first to know when it goes live and to lock in early-bird rewards.